Sales rankings hide part of the work
One customer places large orders, negotiates discounts, calls frequently and requests urgent deliveries. Another buys less but sends complete requirements and approves work quickly. Revenue rankings put the first customer ahead; they reveal little about the effort needed to serve them. To decide where to focus, connect each sale with its operational consequences.
This analysis is not a mechanical instruction to drop less profitable customers. It helps identify commercial terms, internal mistakes and additional services that deserve a conversation.
Build two views without counting costs twice
Start with sales excluding tax and net of credit notes over three to six months. Deduct attributable variable costs: purchases, specific transport, commissions and order-related subcontracting. The result is contribution before other expenses. Bpifrance defines contribution margin as the difference between revenue and variable costs.
Then examine the time involved in preparation, meetings, requests and rework. Apply a documented internal hourly cost to compare service effort. If staff expenditure was already included among the deducted costs, do not count it again. Clearly separate estimated hours from recorded hours.
Fictional example: two customers, two results
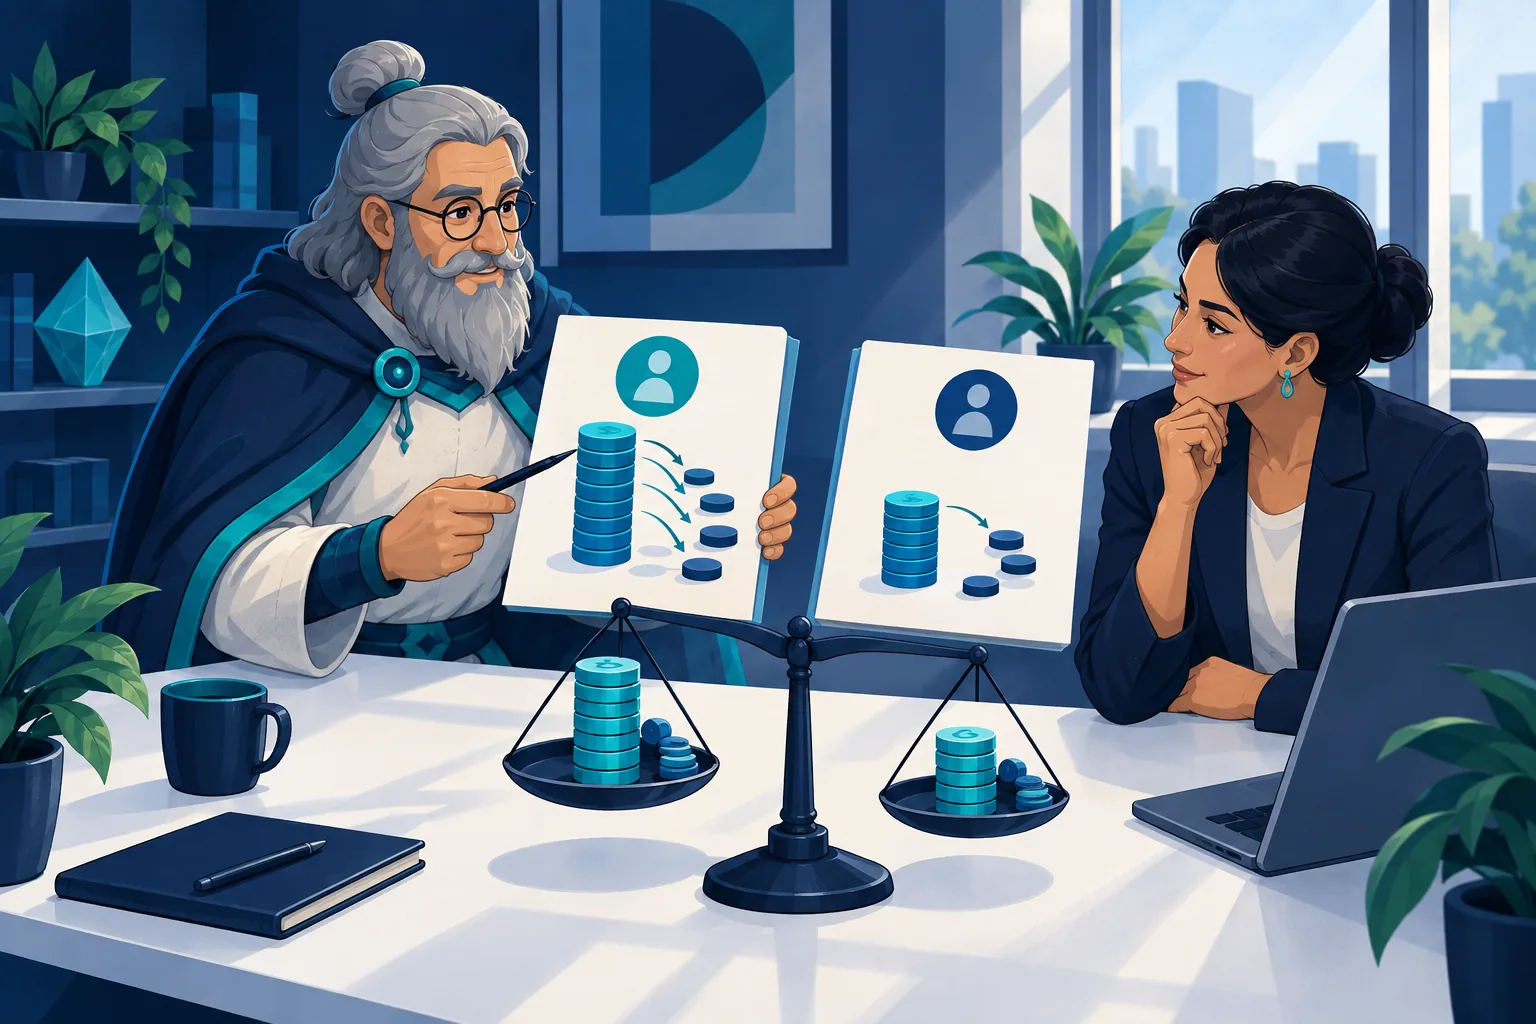
During an invented quarter, customer A generates €20,000 in sales and €12,000 in variable costs, leaving €8,000 contribution. Customer B generates €12,000 in sales and €5,000 in variable costs, leaving €7,000. A contributes more euros; B has a higher contribution rate: 58.3%, compared with 40%.
A also requires 80 hours of internal service, while B needs only 20. Using a fictional comparison cost of €40 per hour, not previously included, the balance after this service cost is €4,800 for A and €6,200 for B. This analytical balance is not net profit: shared expenses still need covering.
Look for a process improvement before negotiating price
Break down customer A’s hours. Did a late approval originate with the customer, or with requirements your team failed to clarify? Did an impossible sales promise create the urgency? A process improvement may help both parties. Otherwise, propose a standard lead time, a minimum order or a paid option for special requests.
Simulate one change at a time and keep the comparison period consistent. If you consolidate deliveries, measure the avoided cost and check that satisfaction and orders do not deteriorate.
A small investigation to start next week
Begin with ten contrasting customer relationships. A well-documented sample helps improve the model before extending the calculation to the whole portfolio.
- Collect sales and credit notes for the same period, using a stable customer identifier.
- Allocate direct expenses and separate amounts that cannot be matched reliably.
- Ask the team to estimate time for three specific tasks, then measure it for five days.
- Choose one service or pricing improvement and schedule a review after thirty days.
What the calculation cannot decide
A relationship may bring repeat business, referrals or useful learning. Make these assumptions explicit instead of assigning invented financial values. Bpifrance explains that overall profitability requires covering every expense: a customer contribution ranking therefore does not replace the income statement. Agree allocation rules with your accountant before making a major commercial decision.